Cross-border payments: towards the next chapter

Opening remarks by Martin Moloney, Deputy Secretary General of the Financial Stability Board, at the OMFIF virtual event on Global financial stability: navigating digital assets and next-generation cross-border payments.

The views expressed in these remarks are those of the speaker in their role as Deputy Secretary General of the Financial Stability Board and do not necessarily reflect those of the FSB or its members.

Watch the remarks and the full discussion

Thank you, Katie-Ann for setting this up. It’s very timely. I’m hoping that by making some slightly extended opening remarks I can give you all a sense of what is on our mind and that my fellow panellists can then add further to inspire our audience to be part of a debate over the next year that I think we really need.

Let me start by recalling that it was in 2020, that the G20 launched our Roadmap. The goal that has now become something of a mantra; it was “to make cross-border payments faster, cheaper, and more transparent and inclusive”. It rolls off the tongue, but making it a reality has proven challenging.

We understood from day one that this was going to be difficult. To calibrate the ambition and to create a degree of accountability, in 2021, we asked the G20 to endorse a set of global quantitative measures, most of which are set for end-2027. And those quantitative measures of what we are trying to achieve tell us we still have a way to go.

With the end of the Roadmap approaching, we have the opportunity to reflect on what we have achieved so far and what further steps would be helpful. And it’s not just for us in the FSB to ask those questions. I think it’s for every other stakeholder as well. We still have work to do under the current Roadmap, which we won’t get distracted from. But I think it is time to ask all our stakeholders to begin thinking about the lessons that can be drawn.

I also suspect the history of the Roadmap is full of lessons for us. The simple fact that we have had to update and reset the Roadmap a number of times is itself striking. This is not plain sailing.

To start the discussion, let me point to a number of reasons which seem relevant to why we are where we are:

The first challenge has to do with market structure and incentives: people will have different views, and payment specialists of course think their work is the most important in the world. But cross-border payments are somewhat marginal to the business model of most of the companies which provide this service. Furthermore, the sense in which there is a traditional competitive market driving quality and innovation is limited, because those markets are complex. Indeed, each major corridor sometimes seems to behave like its own market, with distinct frictions. Regions appear to behave differently from each other. And so on. We talk about global cross border payments, but its more complex than that phrase suggests.

Secondly, we face what I might call ‘exogenous dependencies’: for example, it has become clear that cross-border payments rely heavily on foreign exchange markets which are the largest markets in the world and outside the remit of our roadmap.

Thirdly, technology adoption dynamics are obviously important in cross border payments: we are constantly told that there is immense technological potential for efficiencies and new services; but it remains a fact that the market is dominated by participants who often appear to be seeking second- or even third-mover advantage.

Finally, the necessary political and regulatory authority is widely distributed: there is no global authority with a mandate to make this work well. Even at the domestic level, there is often limited effective coordination. Importantly, the issue cuts across the sensitive division of responsibilities between central banks and finance ministries. At the same time, there are many global standard setters and organisations with an interest. We have tried to work with all of them.

Adding all that up amounts to a real challenge for policy makers. On the one hand, it seems, we may not be able to rely as much as we hoped on competitive markets to resolve issues, even if we do everything we can to make space for competition to work as well as it can. On the other hand, we haven’t got well established global authorities to direct change. Neither the visible nor the invisible hand seems to have a strong grip on this issue.

But it is far from hopeless. Why do I say that? I suspect the FSB back in 2020 did something important in trying to find a way through these challenges. When we set up the Roadmap, we bought into an important simplifying idea: use the FSB’s convening power to smooth out as many as possible of the regulatory and policy impediments to see if market dynamics to improve cost, speed, transparency, and access. We have done that. It was important to do it. The thought was ‘let’s test what competition can achieve’.

As we move towards 2027, however, we now have to ask the difficult question of what the results are telling us about that approach. Has our focus on removing frictions been sufficient? Should we double down on it? Should we pivot to operational planning such as we are currently testing with the jurisdictional and regional action plans we are working on? Or should we step back and just let the technology innovators lead?

Turning to technology innovators first, a much talked about option is whether stablecoins could be the silver bullet. Let’s just remember the numbers. There are varying measures of the volume of cross-border payments, but let’s just say total payments in 2024 were at or around USD 200 trillion. In contrast, the volume of cross-border payments being made by stablecoins is estimated to be only a fraction of this – by some estimates less than 0.2 per cent of total cross border payments in 2025. The order of magnitude tells a clear story: today, stablecoin volumes remain a very small share of total cross-border flows. There is some evidence of exploration of large financial institutional use cases.  Their most immediate value may be as components in hybrid models – integrated with bank money and interoperable FX/settlement – rather than as stand-alone global rails. But neither is more than a possibility at this point.

Turning to our work to reduce frictions. The work has not just been about getting better policy frameworks, it has also been about technical frictions. Let me spend a moment on that. Poor data quality and limited standardisation of data exchange make cross-border payments more complex to process, in turn affecting their speed, price and transparency. Promoting the adoption of common message formats, including conversion and mapping from legacy formats and the use of Legal Entity Identifiers and common protocols for data exchange, does mitigate the frictions.

When ISO 20022 was first introduced in 2004, it marked the beginning of an important journey toward a new era of simpler, more data-rich payments for banks and their customers. One of the original building blocks of our Roadmap in 2020 (building block 14) was adopting ISO-harmonised message formats. Twenty plus years after the original version of the ISO standard, we are at 77% of fast payments systems and 53% of real time gross settlement systems reporting implementation of the messaging standard.

This is good. But it has taken very long time and it’s not complete. Without the extensive work of CPMI, I suspect what has been achieved, would not have been achieved. We also know that implementation is necessary but not sufficient. The value of the ISO standard comes from consistent usage, ensuring rich data and embedding the standard into end-to-end operations; for example, screening, reconciliation, fraud analytics and supervision, not just message conversion.

Extensive efforts here have undoubtedly made a difference. But to fully realise the potential benefits of the ISO standard, continuous development is needed to align the messages to evolving market practices and embed them into operations. For example, whilst ISO 20022 includes enhanced data elements that can strengthen Anti-Money Laundering and Countering the Financing of Terrorism (AML/CFT) measures, a recent study found that many financial institutions continue to rely on traditional screening methods developed for payment messages. ISO 20022 carries more data than legacy messaging formats, so banks could use it to create a fully integrated payments experience, giving them an end-to-end view of operations from initiation and delivery of the payment to exceptions, investigations and reporting. But this requires a pretty large investment.

Our work has also highlighted other challenges where we have sought to promote better practices, but we continue to hear about issues:

  • Data sharing to fight fraud;
  • Smooth processes where capital controls exist;
  • Efficient ways to do sanctions screening;
  • How foreign exchange access restrictions work;
  • Payment versus payment coverage;
  • Opening hours;

How do we get from identifying frictions to global implementation of solutions to those frictions? One of our key reflections is about leadership and regional organisation. This is an area that the International Monetary Fund and the World Bank have done a lot of work on. Don’t jurisdictions need to carefully assign responsibility, and don’t regions need effective regional cooperation structures?

Conclusion

My overall view is this: we are coming to the end of the Roadmap, but not yet the end of the journey. The Roadmap’s goals surely endure? Perhaps the lesson of recent years is that coordination is proving to be the scarce resource.

So, as we look beyond 2027, the question is not simply what we do next, but how we choose to organise ourselves to do it. Is continued friction-removal enough to unlock better outcomes, or do we need corridor-by-corridor or region by region operational plans with clear ownership?

If neither path is sufficient on its own, what blend would be credible and politically sustainable across jurisdictions?

How far should we push standardisation or integration without eroding domestic policy options or privacy protections? 

As technology evolves, should stablecoins and tokenised deposits be complements within integrated models, or catalysts for new rails?

Who will be the champions of a second Roadmap?  

And finally, what should success look like after 2027 – not just in metrics, but in lived experience for people and companies in every region? Maybe speed, cost and transparency are not all equally important to end-users?

I think we need the help of every stakeholder in the system to reflect on where we are and what we should achieve, to convene discussions, to send us submissions to engage with us and each other to make sure a further Roadmap really drives forward to substantive change.

I hope to hear a lot more on these questions today and over the coming months. Thank you for giving me the time to set out those thoughts.
Opening remarks for the FSB 2026 ReSolve Event: Exploring cross-sectoral interconnections and financial stability implications

Remarks by Dominique Laboureix, Chair of the Single Resolution Board, at an event for the Financial Stability Board Cross-Border Crisis Management working groups.

The views expressed in these remarks are those of the speaker in their role as Chair of FSB Resolution Steering Group and do not necessarily reflect those of the FSB or its members.

Ladies and Gentlemen, good morning,

It is a real pleasure to welcome you all today at this Financial Stability Board (FSB) ReSolve event.

I am particularly delighted that this event has finally become a reality. In fact, one of my priorities as the Chair of the Resolution Steering Group (ReSG) was to create more opportunities for the different Cross-Border Crisis Management (CBCMs) groups to come together, exchange experiences and learn from one another across sectors. Too often, we work within our own communities, despite facing many of the same challenges. Bringing together authorities responsible for banking, insurance and central counterparties in one forum was therefore an objective I felt strongly about, and I am very pleased to see it materialising today.

So, first of all, let me thank the Chairs of the three CBCM working groups and, of course, the colleagues at the FSB Secretariat for making this vision a reality. 

This is a unique gathering. For the first time, resolution authorities and members of the different CBCMs are meeting in a truly cross-sectoral setting. That matters because financial crises do not respect sectoral boundaries, and neither should our preparedness.

We have learned over the years that crises rarely remain confined to one institution, one jurisdiction or one market. They spread. They create spillovers across borders, across markets and, increasingly, across industries.

Many of us in this room remember how the global financial crisis unfolded in 2008. Within a matter of weeks, the failure of Lehman Brothers triggered an unprecedented loss of confidence across the financial system. Funding markets froze, liquidity evaporated and panic spread rapidly across borders. Yet it soon became clear that the crisis was not confined to the banking sector. The rescue of AIG demonstrated that vulnerabilities in the insurance sector could also pose systemic risks with global consequences. AIG had built up massive exposures through credit default swaps, effectively providing insurance on structured credit products held widely across the banking system. As the value of those underlying assets deteriorated, AIG faced escalating collateral calls from its counterparties, creating acute liquidity pressures. The risk was not only the failure of a single firm, but the transmission of stress through its extensive network of counterparties, which included major global banks.

Authorities were simultaneously working to preserve the functioning of financial market infrastructures to prevent the disruption from spreading even further. At the time, few fully understood how these contagion channels would operate or how quickly stress could propagate across sectors. That experience reminds us that future crises may again emerge through unexpected channels, and that strengthening our preparedness is essential to reduce the risk of being caught by surprise.

This is even more true today as the interconnectedness that characterises the financial system has only increased, meaning that vulnerabilities can propagate in even more unexpected ways.

That reality requires us to think beyond our traditional boundaries. If crises spill over between countries and sectors, then our readiness must also extend beyond countries and sectors. We need to move from individual preparedness towards what I would call “joint readiness”.

That, ultimately, is the ambition of this event.

Over the next two days, we are not simply exchanging presentations or comparing legal frameworks. We are building a common understanding of the practical challenges we face. We are learning from each other’s experiences. We are strengthening relationships that will prove invaluable when decisions have to be made under pressure. And we are reinforcing the trust that effective crisis management ultimately depends upon.

Cross-sector dialogue is such an important part of this effort. Understanding how different sectors approach preparedness, operational continuity, communication, valuation or cross-border cooperation makes all of us better equipped to deal with complex crises that may not fit neatly within institutional or sectoral boundaries.

In fact, there is one question that I personally hope we will begin to tackle over the next two days. It is perhaps not the most comfortable question, but I believe it is one of the most important. We devote significant attention to making resolution workable within each sector. But do we sufficiently understand the consequences of a resolution across sectors? Could the resolution of a bank generate spillover effects that put an insurer or a central counterparty under stress? Equally, could distress or the resolution of an insurer or a financial market infrastructure have unintended consequences for banks?

These are difficult questions precisely because our objective is not simply to make individual resolution regimes work. It is to ensure that the financial system as a whole remains resilient. If there are cross-sector transmission channels, we need to understand them. If there are unintended consequences, we need to identify them. And if there are gaps in our preparedness, we need to address them before the next crisis tests us.

I do not expect us to answer all these questions over the next two days. But if this event enables us to start that conversation, to challenge some of our assumptions, to learn from one another and to deepen our understanding of cross-sector interdependencies, I would already consider it a great success.

This also brings me to another important point: readiness.

We often speak about legal frameworks, resolution plans and policy standards. These are, of course, essential. They are the foundation upon which effective resolution regimes are built.

But frameworks alone are not enough.

Readiness is where those frameworks become operational. It is where plans are tested against reality. It is where legal powers are translated into practical action. And it is where institutions demonstrate that they can respond effectively under compressed timelines, incomplete information and the pressure that inevitably accompanies a real crisis.

In other words, credibility is built before a crisis, not during one.

Every resolvability assessment completed, every operational capability strengthened, every obstacle identified and addressed, and every cross-border exercise conducted contributes to that credibility. Conversely, every unresolved impediment weakens the confidence that markets and authorities place in our frameworks.

This is why implementation matters so much.

In that sense, the Financial Stability Board has played a fundamental role in establishing the international standards that underpin modern resolution regimes. The recommendations agreed by the FSB have fundamentally strengthened our collective ability to manage financial crises while reducing moral hazard and protecting financial stability.

But those recommendations only achieve their purpose if they are implemented consistently and effectively.

And this is where I would like to recognise the extraordinary contribution made by all of you.

While the decisions and recommendations adopted by the FSB Plenary rightly receive significant attention, it is the daily work carried out within the CBCM working group, and back home of course, that keeps those standards alive.

In many respects, you are the guardians of the FSB’s Key Attributes.

Your work ensures that high-level principles are translated into operational reality. You identify practical challenges, test assumptions, improve coordination, strengthen cooperation across authorities and help jurisdictions implement internationally agreed standards in ways that are effective and credible.

This is painstaking work.

It is highly technical. It often happens behind the scenes. It requires persistence, expertise and an unwavering attention to detail.

Quite simply, the FSB Plenary, supported by the ReSG, provides the strategic direction, but it is your work that transforms international standards into operational reality.

On behalf of the Resolution Steering Group, I would therefore like to express my sincere appreciation and gratitude for everything you do. Your commitment is one of the main reasons why the international resolution framework continues to evolve and remains credible.

Over the next two days, I encourage all of you to make the most of this unique opportunity. Challenge each other. Share your practical experiences. Discuss not only what has worked well but also what has proved difficult. Some of the most valuable lessons come from understanding where implementation remains challenging and where collaboration can be strengthened.

If we leave this meeting with a deeper understanding of one another’s perspectives, stronger professional relationships and new practical insights that improve our collective preparedness, then this event will have achieved exactly what it set out to do.

Because ultimately, preparedness goes beyond trying to avoid incidents and crises. It is about assuming that they will happen and imagining solutions to fix them. This is a great forum to discuss just that!

And while crises may begin in one institution, it is impossible to know where they will go.

We must be ready together.

Thank you very much, and I wish you an engaging and productive ReSolve event.

Opening remarks on sound practices for artificial intelligence

Remarks by Michelle W. Bowman, Vice Chair for Supervision, Board of Governors of the Federal Reserve System, at Financial Stability Board Virtual Outreach Event.

The views expressed in these remarks are those of the speaker in their role as Chair of the FSB Standing Committee on Supervisory and Regulatory Cooperation and do not necessarily reflect those of the FSB or its members.

Thank you for the opportunity to join you today to discuss the Financial Stability Board’s (FSB) consultation report on Sound Practices for Responsible Adoption of Artificial Intelligence. Both Federal Reserve staff and staff from the FSB Secretariat are eager to consider and incorporate feedback on the consultation report so that we can finalize the report later this year as a US G20 deliverable.

Before offering a few thoughts about the report itself, I want to thank Hern Shin Ho from the Monetary Authority of Singapore. Hern Shin led the FSB work stream that produced this report in a very compressed timeframe, and I would also like to recognize and thank the FSB Secretariat staff who supported this work. Finally, I would like to thank our US colleagues at the Treasury and the SEC who also collaborated with us to produce this report.

As many of you know, I chair the FSB’s Standing Committee on Supervisory and Regulatory Cooperation. In setting out my priorities late last year, I initiated work on a set of sound practices for financial institutions to consider in the responsible adoption and use of Artificial Intelligence (AI). Since that time, AI has continued to rapidly evolve, and financial institution use of AI has expanded. In light of these ongoing developments, it is important to engage the public to discuss the potential benefits of AI and the risks and other challenges that could arise with its use in our report. The report also describes the ways in which financial institutions, including banks, are already successfully addressing and managing AI use risks, with the broader goal of responsible innovation that benefits financial institutions and their customers.

The Federal Reserve has been monitoring bank usage of AI for nearly a decade. We have seen a noticeable increase in the use of AI by banks of all sizes, and we have seen a variety of use cases. Our focus has been on supporting institutions that want to innovate responsibly by leveraging AI tools in their operations. Our work in the US has helped to inform the FSB’s report.

A central element of managing AI risks is understanding the specific use cases. In the FSB’s report, we provided a variety of examples, including some in-depth case studies, to illustrate the types of governance and controls that might be appropriate in similar situations. To be clear, these practices are not the only way to adopt and use AI responsibly or to manage AI risks.
Another important aspect to highlight in this report is whether the use of AI is material. From my perspective, financial institutions should be specific about how they use AI and whether it is material to their business operations or legal and regulatory obligations. That actual use and materiality will help inform the type and intensity of the governance and controls that should be applied for the specific AI deployment. In the report, we emphasized that lower-risk uses of AI should receive a lighter supervisory and regulatory touch.

Similarly, the report also includes a significant focus on proportionality. What works or is a consideration for larger institutions using AI in complex applications is not appropriate for smaller institutions with less complex AI uses. As I noted, our focus is on promoting innovation at financial institutions of all sizes, not just the largest ones. This report provides clear guidance to all institutions, including smaller institutions. So, I welcome feedback about whether the report strikes the appropriate balance on proportionality as it relates to AI adoption and use.

To close, this report is an important first step as we consider how financial institutions can use AI responsibly. As you provide feedback, I encourage you to identify areas where the sound practices may be too prescriptive or where they fail to adequately account for differences in institutional size, complexity, and risk profile. Equally important, help us identify where we may not have adequately addressed material risks or where additional clarity would help institutions manage AI-related risks more effectively. We need to ensure these practices support responsible innovation across the financial system while maintaining appropriate safeguards, especially for higher-risk applications.

The feedback we hear from you today and throughout the public comment period will help inform our final report delivered to the US G-20 presidency later this year. I am pleased with the international collaboration so far on this work and look forward to improving on this in the final report later this year.

Virtual outreach event on FSB sound practices for financial institutions’ responsible adoption of artificial intelligence

On 7 July 2026 the FSB hosted a virtual event as part of the consultation process for its proposed sound practices for financial institutions’ responsible adoption of AI.

On 10 June 2026, the Financial Stability Board published a consultation report on Sound Practices for Responsible Adoption of Artificial Intelligence (AI) to help financial institutions responsibly navigate AI adoption in a rapidly evolving technological landscape.

As part of its consultation, the FSB hosted a virtual outreach event on Tuesday 7 July 2026. The event aimed to inform stakeholders about the consultation and to gather preliminary perspectives on the topics covered in the consultation report.

FSB holds a roundtable on audit quality and structural shifts in the global audit industry

Rapid technological progress and shifts in the ownership of accountancy and audit firms bring both significant opportunities and financial stability risks.

On 18 June 2026, the Financial Stability Board (FSB) convened a roundtable to explore the potential financial stability implications of structural shifts in the global audit industry. In recent years, the adoption of new technologies, including artificial intelligence, has grown significantly in external audits, driving investment needs that have often resulted in changes to audit firm ownership. The roundtable aimed to enhance understanding of how these developments may impact audit quality, a critical factor in safeguarding financial stability.

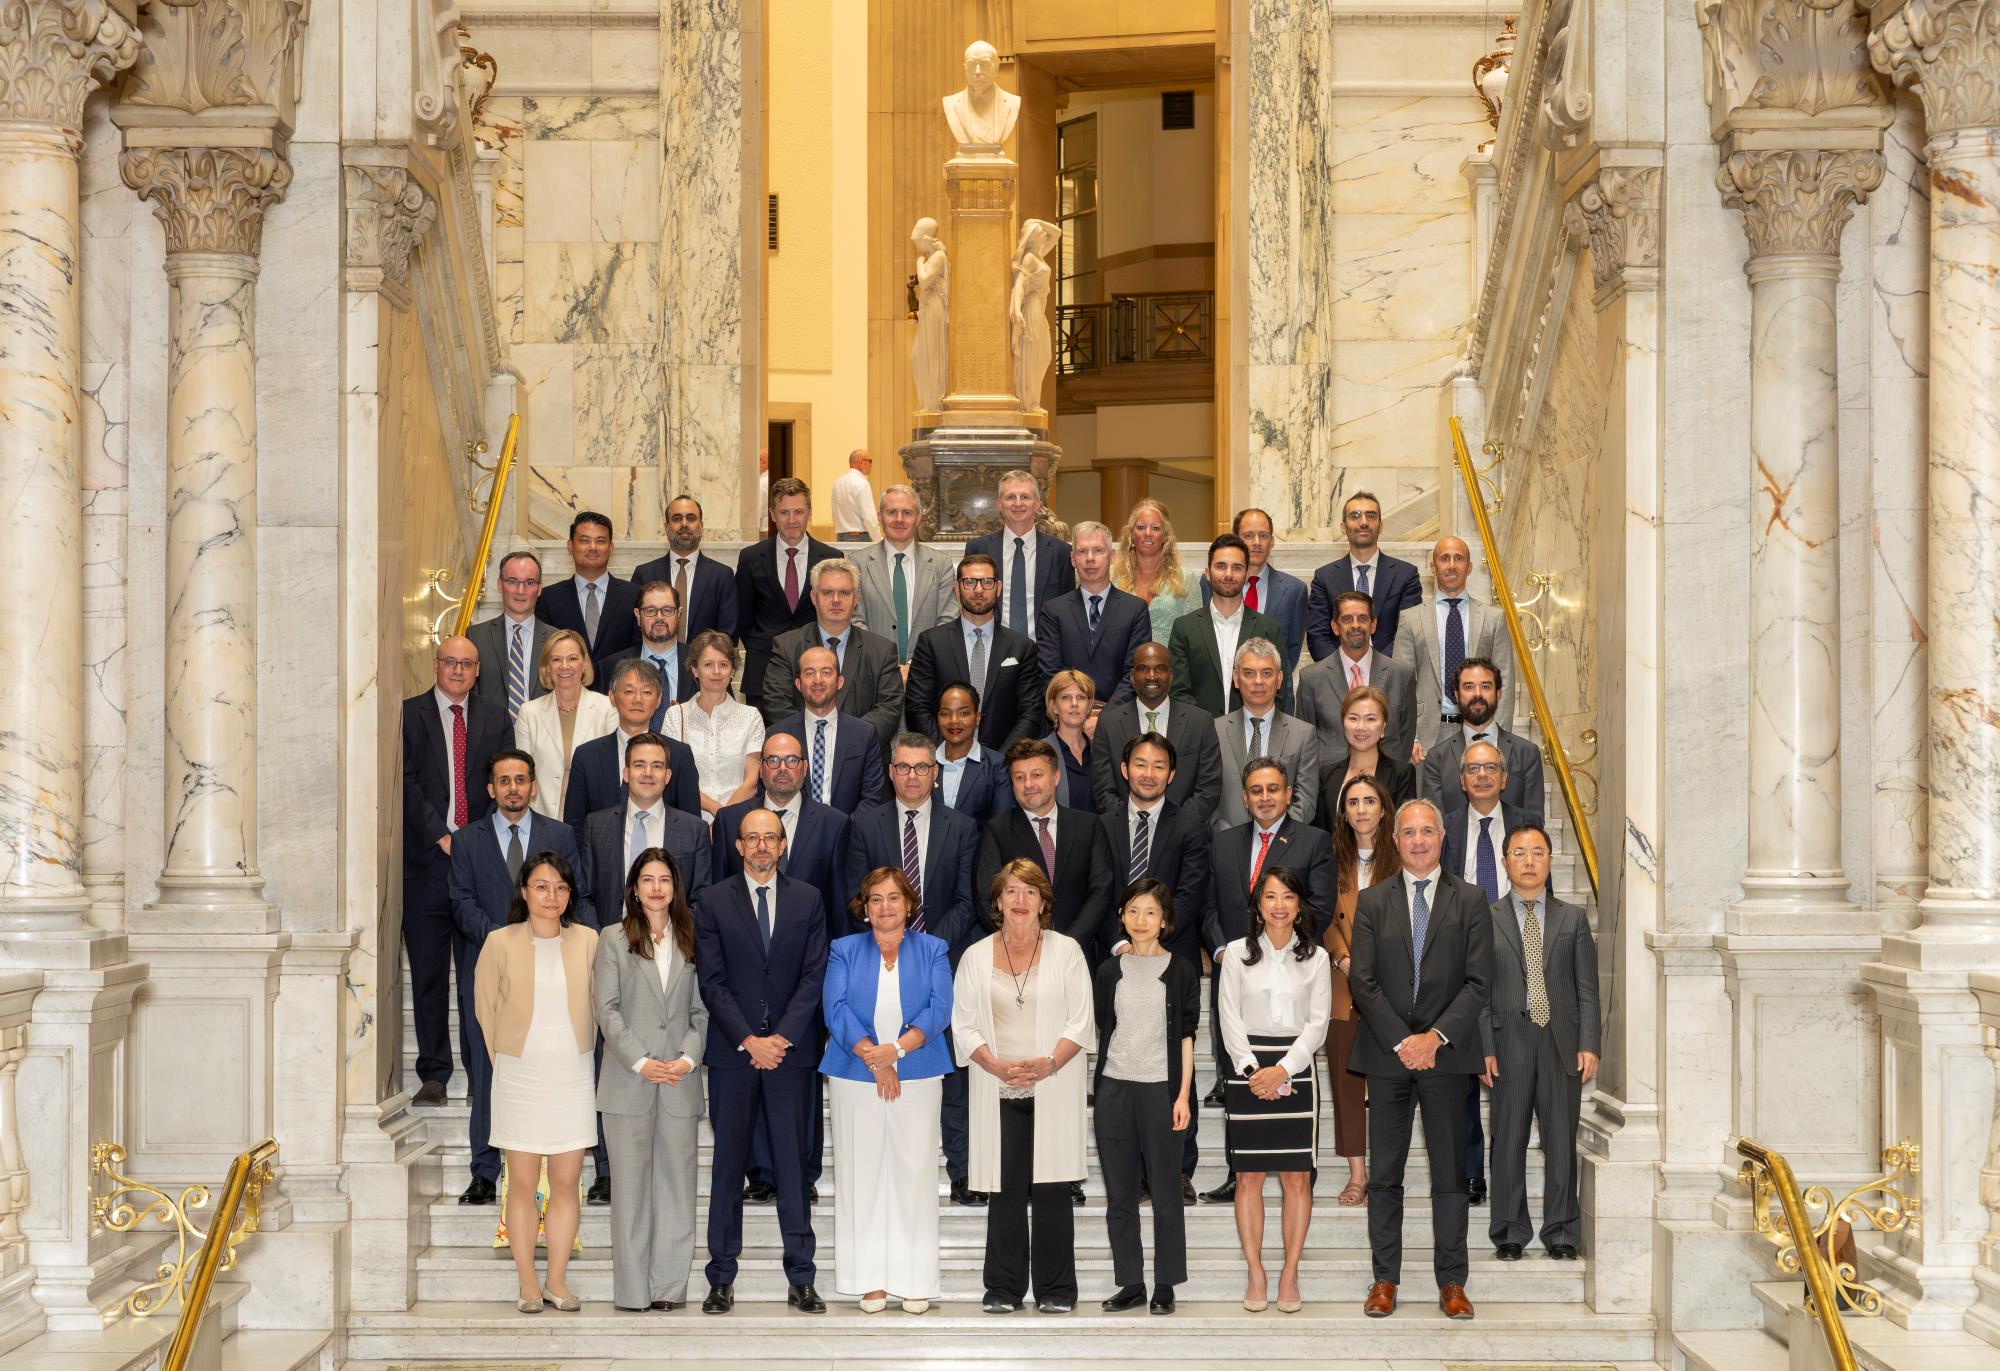
FSB Roundtable on audit quality, Banco de España, 17-18 June 2026.

The meeting, which was hosted by the Bank of Spain in Madrid, was chaired by Soledad Núñez, Deputy Governor of the Bank of Spain. Participants included senior representatives from FSB member authorities and standard-setting bodies; audit oversight bodies; the International Federation of Accountants (IFAC); the International Forum of Independent Audit Regulators (IFIAR); the Committee of European Auditing Oversight Bodies (CEAOB); the international standard-setting bodies for auditing, assurance, and ethics in accountancy and their oversight body, the Public Interest Oversight Board (PIOB); the six largest global audit networks and a local audit firm, as well as other key stakeholders.

Discussions focused on the implications of changes to audit firm ownership and the potential risks and opportunities arising from the emergence of new technologies in the accountancy and audit profession. Participants reviewed the major factors driving these trends and the practices observed in different parts of the world. They exchanged views on how these changes may affect standard-setting and the adequacy of existing standards. The discussion also covered ways to enhance audit quality against the backdrop of the adverse trend observed in audit inspection findings in the past few years.

Sound Practices for Responsible Adoption of Artificial Intelligence (AI): Consultation report

| PDF full text (985 KB)

Financial institutions are leveraging AI to transform operations and services, but its rapid adoption may also amplify or introduce risks that need to be identified and managed appropriately.

Responsible AI adoption allows financial institutions to harness opportunities and benefits while minimising associated risks. In particular, financial institutions need to understand and remain updated on the opportunities and risks of AI, and respond with the appropriate adoption strategy and guardrails to manage evolving associated risks. At the financial system level, responsible AI adoption reduces risks to financial stability. 

This report highlights the benefits and risks associated with AI use in the financial system.

To facilitate responsible AI adoption by financial institutions, the report proposes a menu of 12 sound practices that financial institutions could apply in their organisation-wide AI governance and management of the relevant stages of AI development and deployment (AI lifecycle). The report includes case studies drawn from real-world AI implementation practices by financial institutions. These case studies illustrate how the sound practices may be applied in practice and, where relevant, how they can be applied proportionately.

The sound practices aim to help the board and senior management of financial institutions as they consider business strategy, technology adoption, and risk management in an increasingly AI-enabled environment. The report builds on existing and ongoing work by the FSB and other standard-setting bodies, as well as national and regional financial authorities. It also incorporates insights from a range of stakeholders across the financial system, including financial institutions and their technology vendors.

Questions for consultation
  1. Do you agree with the benefits and risks of AI adoption by financial institutions described in this report? Are there any substantive benefits or risks not covered?
  2. Are the sound practices sufficiently comprehensive and clear to enable financial institutions’ responsible AI adoption?
  3. Do the sound practices strike an appropriate balance between managing risks relating to all forms of AI, and addressing some of the risks relating to emerging and new complex forms of AI, such as GenAI and agentic AI?
  4. Are the sound practices sufficiently flexible to accommodate and address newer types of AI and responsible adoption over time? 
  5. Do the case studies in this report sufficiently highlight how different types of financial institutions can benefit from responsible AI adoption? Are there additional case studies for inclusion in the report? If so, please provide such case studies, particularly for nonbanks.
  6. Do the case studies in this report provide actionable insights for financial institutions in their responsible AI adoption?
  7. Are the definitions in the glossary clear and aligned with industry sound practices, including recent developments in AI? 

FSB consults on sound practices for the responsible adoption of artificial intelligence (AI)

Press enquiries:
+41 61 280 8477
[email protected]
Ref: 9/2026

  • The FSB is seeking feedback on its proposed sound practices, which aim to help financial institutions responsibly navigate AI adoption in a rapidly evolving technological landscape.
  • The 12 sound practices cover organisation-wide governance, as well as management of different stages of AI development and deployment.
  • The board and senior management of financial institutions are strongly encouraged to reference the sound practices as they consider business strategy, technology adoption, and risk management in an increasingly AI enabled environment.

The Financial Stability Board (FSB) today published a consultation report on Sound Practices for Responsible Adoption of Artificial Intelligence (AI). The sound practices focus on AI-specific aspects and risks that are relevant to financial institutions and financial stability.

The FSB has identified 12 sound practices to help financial institutions responsibly adopt AI. The sound practices build on and are broadly compatible with existing and ongoing work by the FSB and other standard-setting bodies. They seek to foster coordination, cooperation and information-sharing among stakeholders, including financial institutions and supervisors, within and across jurisdictions. The sound practices cover:

  • organisation-wide AI governance (sound practices 1 to 4);
  • the management and mitigation of AI risks through the different stages of AI development and deployment (sound practices 5 to 10); and
  • the management of AI-related cyber, information and communication technology, and third-party risks (sound practices 11 and 12).

The FSB strongly encourages the board and senior management of financial institutions to reference this toolkit as they consider business strategy, technology adoption, and risk management in an increasingly AI enabled environment. The sound practices are not intended to establish an international standard, to impose a prescriptive approach for responsible AI adoption by financial institutions, nor to influence business decisions in adopting a certain AI technology. They are also not developed to address recent risks that have emerged related to frontier AI models, although some sound practices would help financial institutions respond to such risks.

Michelle Bowman, Chair of the FSB Standing Committee on Supervisory and Regulatory Cooperation (SRC) and Vice Chair for Supervision of the Board of Governors of the Federal Reserve System of the United States of America, said “This report establishes clear safeguards for financial institutions to adopt, innovate, and use AI responsibly. The report reflects significant collaboration among FSB members on an accelerated timeframe to keep pace with the rapid changes from advancements in AI. I look forward to receiving public feedback on this report, so that a final report can be issued later this year as a US G20 deliverable.”

Ho Hern Shin, Lead of the SRC Workstream on Artificial Intelligence and Deputy Managing Director of the Monetary Authority of Singapore, said “The recent developments in frontier AI models highlight the dynamic nature of this technology and the rapid pace at which its capability evolves. The FSB’s sound practices are designed to help financial institutions navigate their AI adoption responsibly in a rapidly changing technology landscape.”

The FSB is inviting comments on this consultation report and the questions set out within it. Responses should be submitted via this secure online form by 22 July 2026. All responses will be published on the FSB website unless respondents request otherwise. The final report will be published in October 2026. 

Notes to editors

The FSB assessed the financial stability implications of AI in the financial system in 2017, followed by an update in 2024. This toolkit builds on and is broadly compatible with this and ongoing work by the FSB and other standard-setting bodies, as well as by national and regional financial authorities.

The FSB coordinates at the international level the work of national financial authorities and international standard-setting bodies and develops and promotes the implementation of effective regulatory, supervisory, and other financial sector policies in the interest of financial stability. It brings together national authorities responsible for financial stability in 24 countries and jurisdictions, international financial institutions, sector-specific international groupings of regulators and supervisors, and committees of central bank experts. The FSB also conducts outreach with approximately 70 other jurisdictions through its six Regional Consultative Groups.

The FSB is chaired by Andrew Bailey, Governor of the Bank of England. The FSB Secretariat is located in Basel, Switzerland and hosted by the Bank for International Settlements.

FSB regulatory and supervisory modernisation symposium

The Financial Stability Board (FSB) hosted a Modernisation Symposium on 9 June 2026 in Basel, bringing together representatives of authorities, academia, and industry to discuss methods and challenges of regulatory and supervisory modernisation. The event was part of the FSB’s work to promote well-aligned modernisation efforts and support members in making regulation and supervision more effective.

Key discussions during the symposium focused on the drivers of change in regulatory and supervisory frameworks, the use of cost-benefit analysis, and tailoring/proportionality in regulatory and supervisory processes. Participants explored challenges such as addressing technological advancements, and ensuring a level playing field across jurisdictions. The insights shared during the event will contribute to a report that the FSB will submit to the G20 in October this year.

FSB Regional Consultative Group for Europe meets in Vienna

The Financial Stability Board (FSB) Regional Consultative Group for Europe (RCG Europe) convened on 2-3 June 2026 in Vienna, hosted by Oesterreichische Nationalbank. The meeting brought together senior officials from central banks, financial authorities, and regulatory bodies across the region to discuss key financial stability issues.

Co-chaired by Antoine Martin, Vice Chairman of the Governing Board of Swiss National Bank, and Marja Nykänen, Member of the Board of the Bank of Finland, the meeting addressed the following topics:

  • the FSB’s work programme for 2026;
  • global and regional financial vulnerabilities;
  • financial stability implications of advanced AI models; and
  • system-wide exploratory stress testing.

Members also participated in a roundtable discussion on private credit, focusing on its growth in Europe, liquidity risks, and vulnerabilities related to retail investor involvement in private credit funds.

FSB Plenary highlights potential new vulnerabilities to financial stability

Press enquiries:
+41 61 280 8477
[email protected]
Ref: 8/2026

The Financial Stability Board (FSB) Plenary met on 1 June 2026 in London, United Kingdom. Members discussed vulnerabilities in the global financial system; sound practices for artificial intelligence (AI) adoption by financial institutions; regulatory and supervisory modernisation initiatives; implementation monitoring; and data challenges related to nonbank financial intermediation (NBFI).

Financial system vulnerabilities

Members discussed the most prominent vulnerabilities in the global financial system, and how the global economic outlook has evolved since their previous meeting in November 2025. Members expressed particular concern that a combination of shocks could concurrently trigger multiple vulnerabilities, threatening financial stability. Key vulnerabilities remain elevated, although the financial system remains resilient. Asset valuations are still high and risk premiums compressed. Sovereign debt continues to be elevated in a context of high public deficits and shortening debt maturities, leaving government bond markets vulnerable to shocks and changes in investor risk appetite, especially given the increased use of leveraged trading strategies in these markets. Private credit usage has grown rapidly, and parts of the sector remain untested in a prolonged economic downturn. In addition, operational outages at critical nodes in the financial system could lead to disruptions. Members also expressed specific concerns about the impact of these global conditions on emerging market economies.

The Plenary highlighted two new developments that have further complicated the risk landscape. First, the conflict in the Middle East has led to ongoing concern about energy and commodity markets and the potential impact on countries dependent on commodity imports. Inflation has gone up, and bond yields have increased. While financial markets have continued to function well so far, uncertainty and volatility are heightened. Second, the unveiling of powerful frontier AI models has concerned regulators and market participants. Such models may sharply increase cyber risks, and patching efforts are important, but may add to problems if rushed or poorly executed.

Sound practices for adoption of artificial intelligence by financial institutions

The Plenary welcomed the timely report on sound practices for financial institutions’ responsible AI adoption developed at the request of the US G20 Presidency. The FSB will publish the report for consultation in the coming weeks, with the final report to be delivered to the G20 Finance Ministers and Central Bank Governors in October.

Regulatory and supervisory modernisation

Many FSB members are reviewing their regulatory and supervisory policies, including supervisory practices, to assess whether they are well suited for changes in the financial system, to facilitate economic growth, and to remain forward looking and adaptive to current and future material risks, without compromising resilience. In this context, the Plenary reviewed the findings from a stocktake of members’ ongoing modernisation initiatives. The stocktake found that modernisation efforts are widespread across jurisdictions and authorities, covering both regulation and supervision. Frequently, they represent an ongoing or iterative practice aimed at ensuring effectiveness. Members agreed to continue work in this area, consistent with the view that financial stability is necessary for robust economic growth.

Implementation monitoring

The FSB Plenary discussed how the FSB’s processes for developing recommendations could better support positive implementation outcomes. The FSB’s Implementation Monitoring Review will make recommendations for improving these processes later this year. Members reiterated the importance of timely and consistent implementation and their commitment in this regard.

NBFI data challenges

Members discussed the importance of progressing efforts to monitor risks involving leveraged strategies in sovereign bond markets. The FSB Plenary received an update from the FSB Nonbank Data Task Force on related data challenges. The discussion focused on risk identification and monitoring frameworks, public disclosure, and cooperation between authorities, including those in offshore financial centres. The Plenary also discussed how best to engage with stakeholders on these issues.

Conclusion

“There is growing concern over new vulnerabilities to global financial stability,” commented Governor Andrew Bailey, Chair of the FSB. “Heightened uncertainty and rapid transformation within the financial system and beyond underscore the need for robust vigilance and sustained international cooperation to address shared challenges.”

Notes to editors

The FSB coordinates at the international level the work of national financial authorities and international standard-setting bodies and develops and promotes the implementation of effective regulatory, supervisory, and other financial sector policies in the interest of financial stability. It brings together national authorities responsible for financial stability in 24 countries and jurisdictions, international financial institutions, sector-specific international groupings of regulators and supervisors, and committees of central bank experts. The FSB also conducts outreach with approximately 70 other jurisdictions through its six Regional Consultative Groups.

The FSB is chaired by Andrew Bailey, Governor of the Bank of England. The FSB Secretariat is located in Basel, Switzerland and hosted by the Bank for International Settlements.